


A typical Warsaw transaction in Q2 2026 was close to PLN 16,700–16,800 per square metre, but that number is a benchmark—not a valuation.
NBP recorded an average transaction price of PLN 16,783/m² for new apartments and PLN 16,723/m² for existing stock. Asking averages were higher on both markets. District, street, building, condition, floor, layout and legal status can move an individual apartment far away from the citywide mean.
The useful question is not “What is the average price in Warsaw?” It is “What should this specific apartment be worth to this buyer after purchase costs, fit-out or renovation, service charges and realistic resale or rental demand?” That is the level at which a market statistic becomes a purchase decision.
Warsaw Investor Care works exclusively on the buyer’s side. We search across new-build and resale stock, compare micro-locations and complete costs, organise viewings, support negotiation and coordinate the legal, technical and post-purchase stages for international clients. This guide shows the market framework we use before an apartment reaches a shortlist.
Send the amount, intended use, financing method and preferred timing. We can help turn broad market averages into a focused buyer brief and a shortlist of real properties.
The market moved, but asking and transaction prices moved differently.
Four numbers describe Warsaw more honestly than one headline average.
 Warsaw is one market only at city scale. Individual streets and buildings form very different price segments.
NBP’s Q2 figures show positive quarterly movement on both markets. Annual growth was much stronger in asking prices than in completed transaction averages, especially on the primary market. That does not prove that every listing is negotiable by a fixed percentage. The offer and transaction samples can differ by timing, mix, location and quality. It does show why a buyer should not use a portal average as the final value of a particular property.
| Warsaw market | Offer price | Transaction price | Difference between averages | Correct interpretation |
|---|---|---|---|---|
| Primary market | PLN 18,488/m² | PLN 16,783/m² | PLN 1,705/m² · 9.2% | Different market samples; not an automatic developer discount |
| Secondary market | PLN 19,059/m² | PLN 16,723/m² | PLN 2,337/m² · 12.3% | Different samples and property mix; verify comparables before negotiating |
Primary source: Narodowy Bank Polski — BaRN residential price database. Publication context: NBP quarterly real-estate information.
Do not compare an asking price with a transaction average as if they were the same thing.
Most misleading Warsaw comparisons begin by mixing data definitions.
 A market headline is useful for orientation. Negotiation needs evidence from the exact submarket.
The seller’s or developer’s starting position
It can include optimistic pricing, premium units, parking or storage handled separately, staged discounts and apartments that have remained unsold for different reasons.
The value recorded for completed deals
It is closer to actual market behaviour but arrives with a lag and still represents an average of different locations, buildings, sizes and conditions.
The middle observation
A median can reduce the influence of extreme values, but it remains only as useful as the sample, period and geographic area behind it.
The number relevant to one apartment
Good comparables should match location, building type, size, floor, condition, legal title, lift, balcony, parking and transaction timing as closely as possible.
A seller may quote a district portal average based on current listings. A buyer may quote the citywide NBP transaction average. Both numbers can be genuine and still fail to value the apartment. The gap between them should start the analysis, not finish it.
Before making an offer, we compare the listing with relevant competing stock, available transaction evidence, renovation or finishing exposure and the property’s specific weaknesses. The commercial approach is built for that apartment—not copied from a citywide percentage.
What does a Warsaw budget buy at the citywide average?
A simple benchmark is useful only when the money needed after the purchase remains visible.
 The same budget can mean a compact central unit, a larger metro apartment or a property needing substantial work.
| Purchase-price budget | At primary transaction average | At secondary transaction average | What the calculation excludes |
|---|---|---|---|
| PLN 750,000 | Approx. 44.7 m² | Approx. 44.8 m² | Taxes, notary, legal review, agent, currency, fit-out, renovation, parking and storage |
| PLN 1,000,000 | Approx. 59.6 m² | Approx. 59.8 m² | The same additional costs and all location or quality premiums |
| PLN 1,500,000 | Approx. 89.4 m² | Approx. 89.7 m² | The same additional costs and the effect of premium segments |
These are mathematical illustrations using the Warsaw-wide NBP transaction averages. They are not promises about available apartments. A buyer may reach much less area in a prime new project or a renovated central tenement and more area in an outer district, older building or property requiring work.
The correct starting point is the complete-capital limit. Reserve the amount needed for purchase costs, immediate works, furniture, contingency and any time before rental income begins. Only the remaining acquisition budget should be divided by a price-per-square-metre assumption.
One budget should produce more than one search route.
For an international buyer, WIC can compare a compact central property, an established metro district and a newer outer-market option under the same total-capital ceiling. This prevents a district preference from hiding a materially better apartment elsewhere.
We can structure the search around the acquisition price, purchase costs, condition, furnishing or renovation and the intended use of the property.
Warsaw’s average disappears at street level.
Use the city number as a benchmark, then move quickly into district, micro-location and building evidence.
Warsaw has 18 administrative districts and several distinct residential markets inside many of them. Śródmieście alone includes prestigious streets, busy transport corridors, post-war blocks and pre-war buildings with very different technical and legal histories. Wola combines premium towers, mature estates and major new-development zones. Mokotów ranges from established residential areas to newer office-linked stock. Outer districts can vary from dense metro neighbourhoods to low-rise and house-dominated locations.
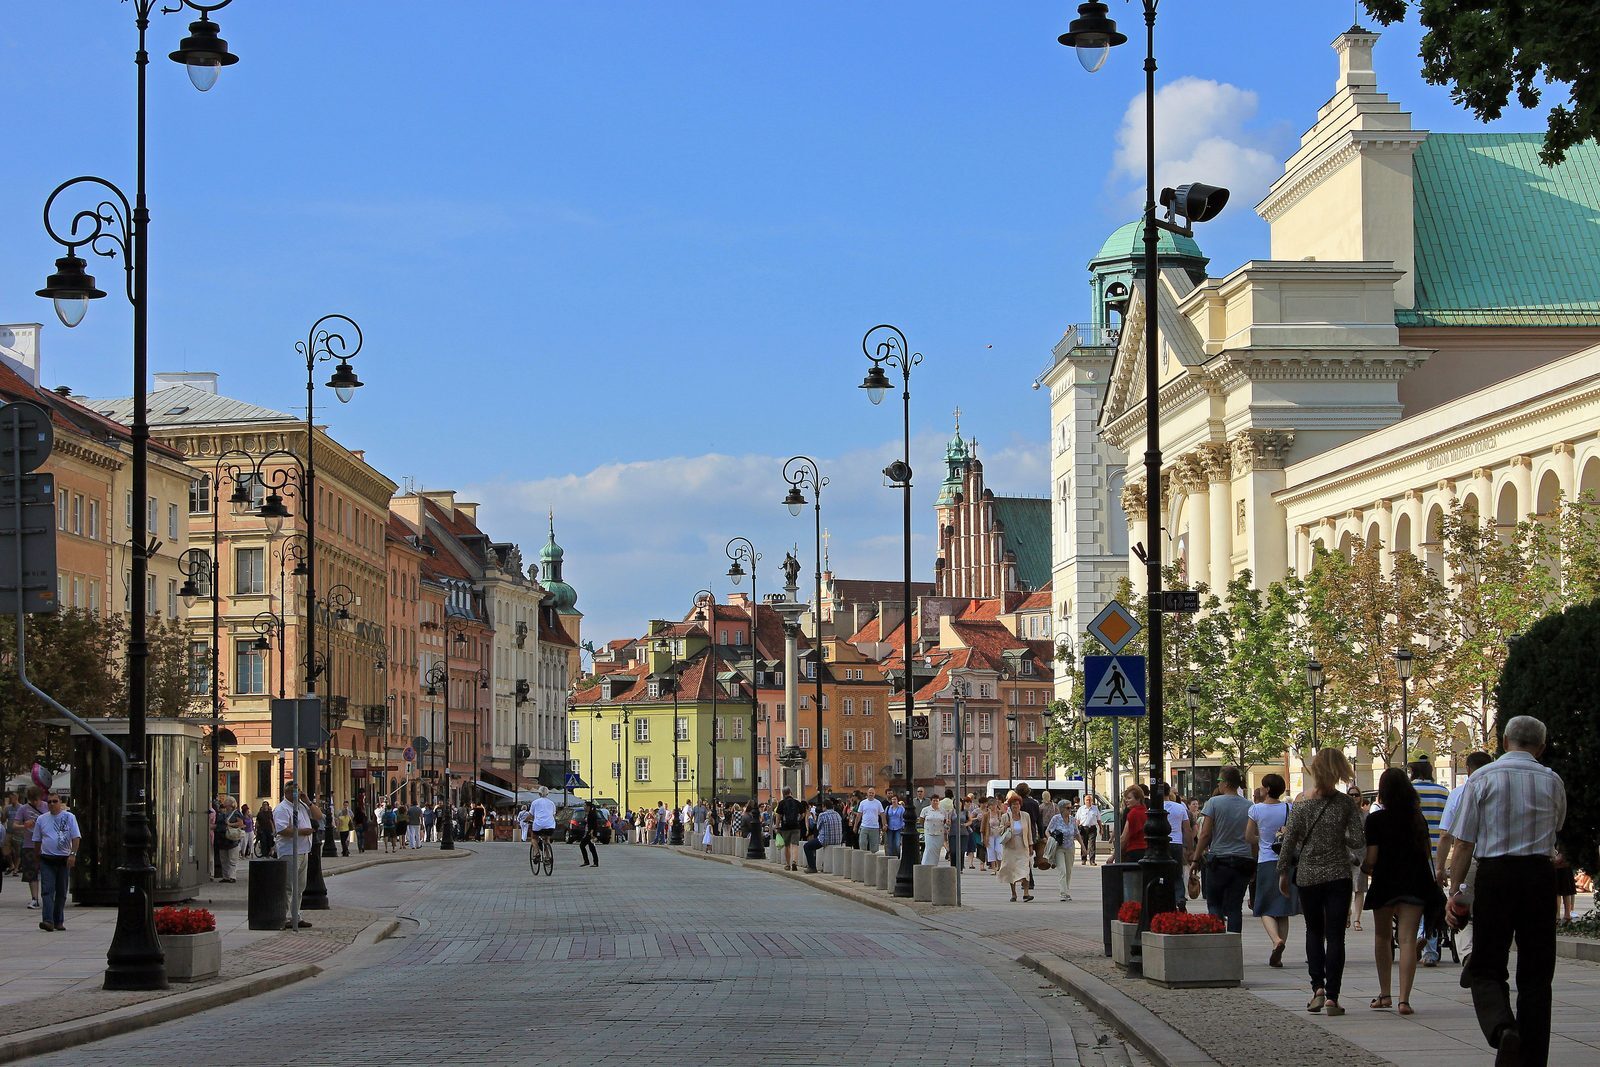
Śródmieście
Premium access, mixed building stock and street-level variation.
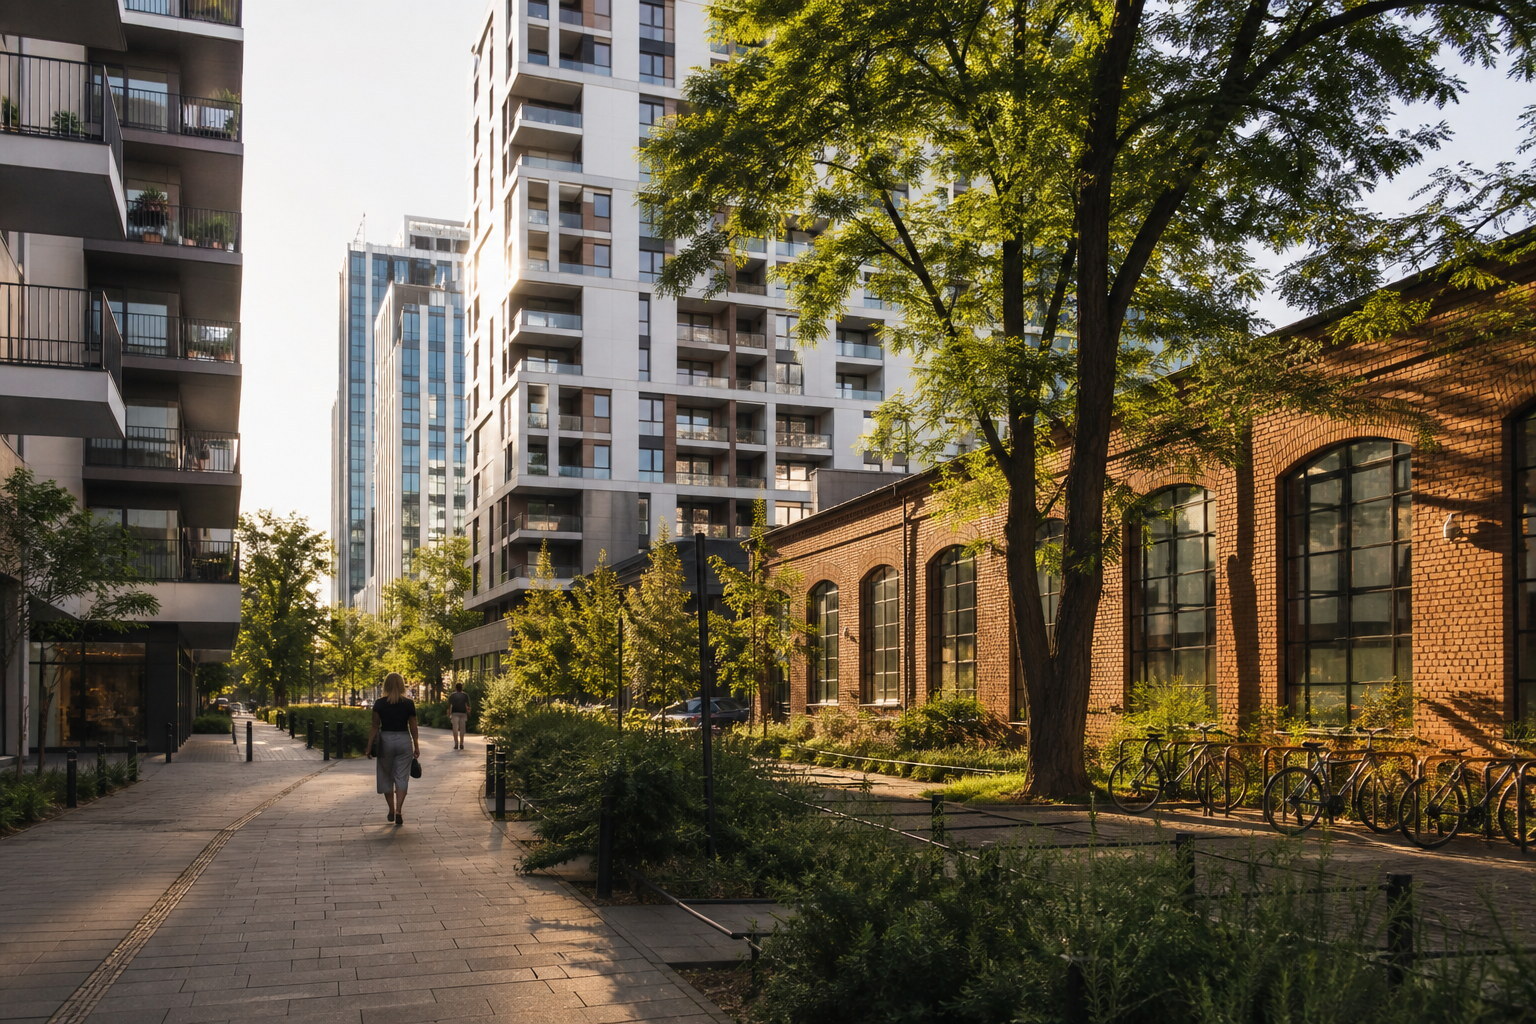
Wola
New supply, M2 access and several distinct buyer segments.
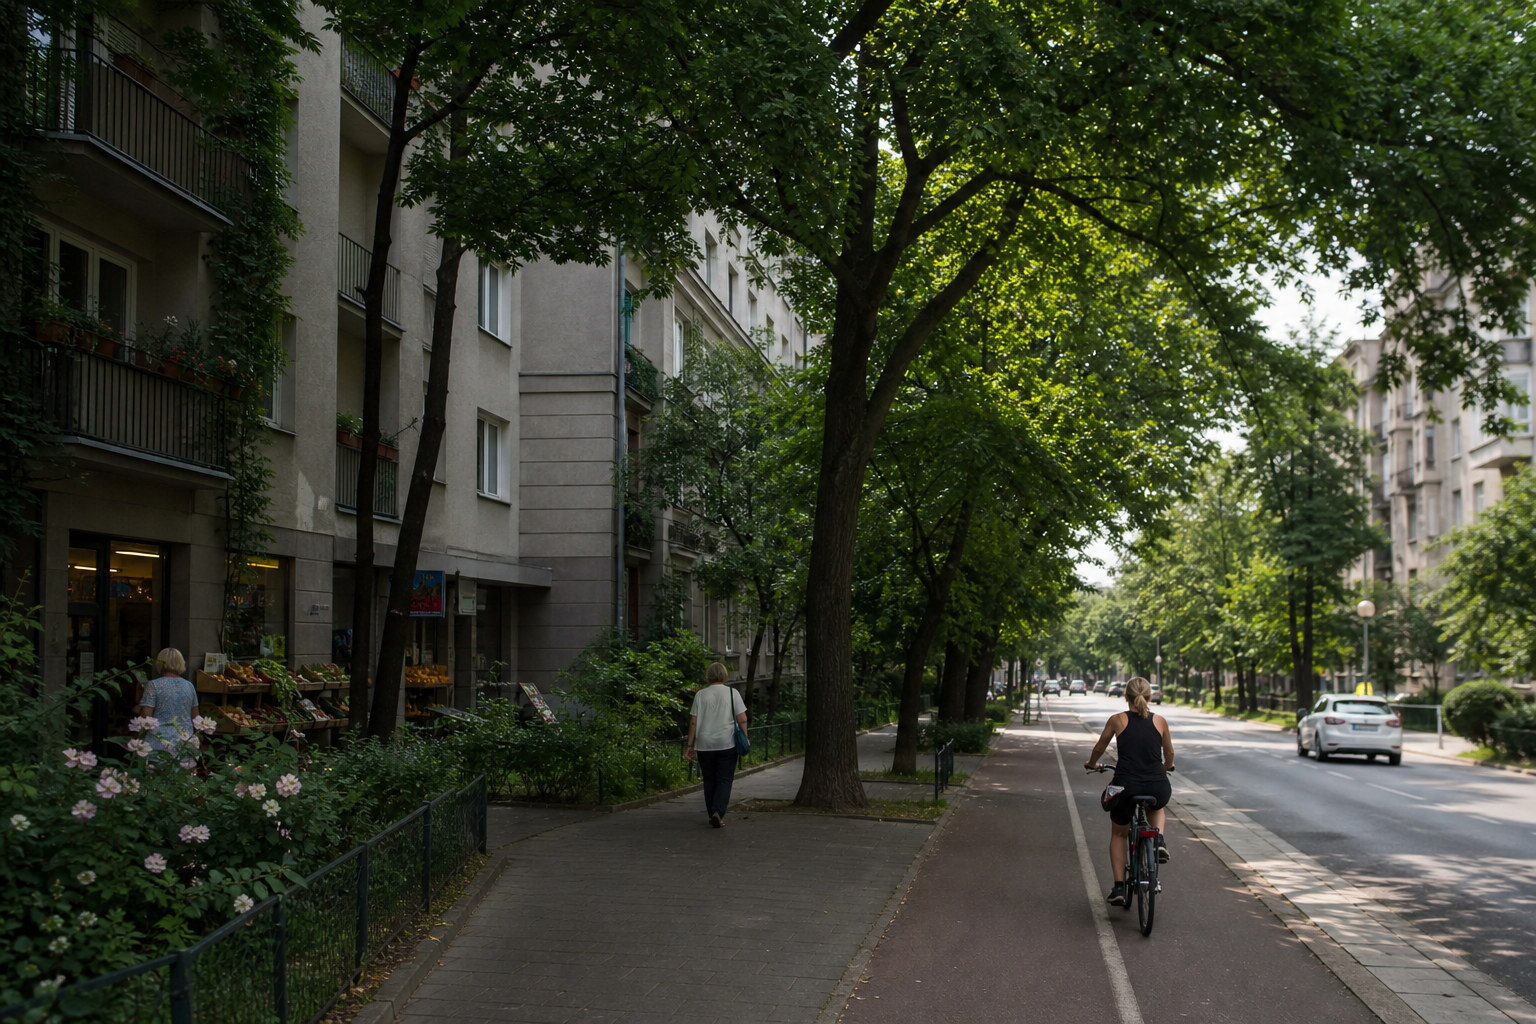
Mokotów
Broad demand, M1 access and highly varied submarkets.
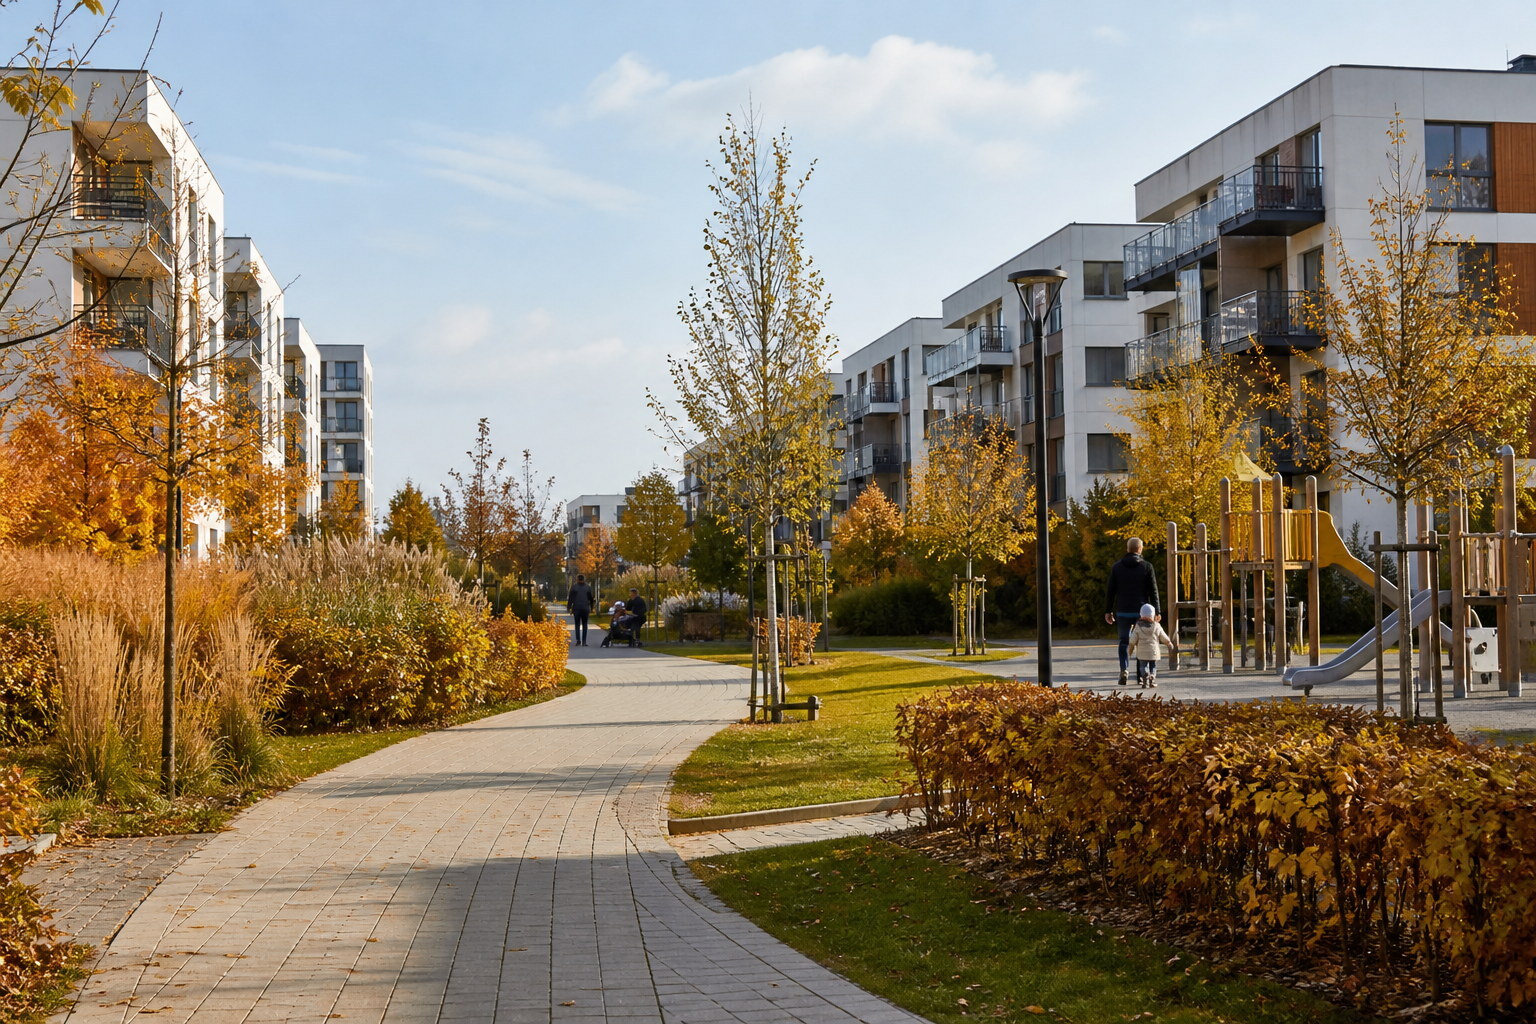
Ursynów
Complete neighbourhoods, family use and direct M1 routes.
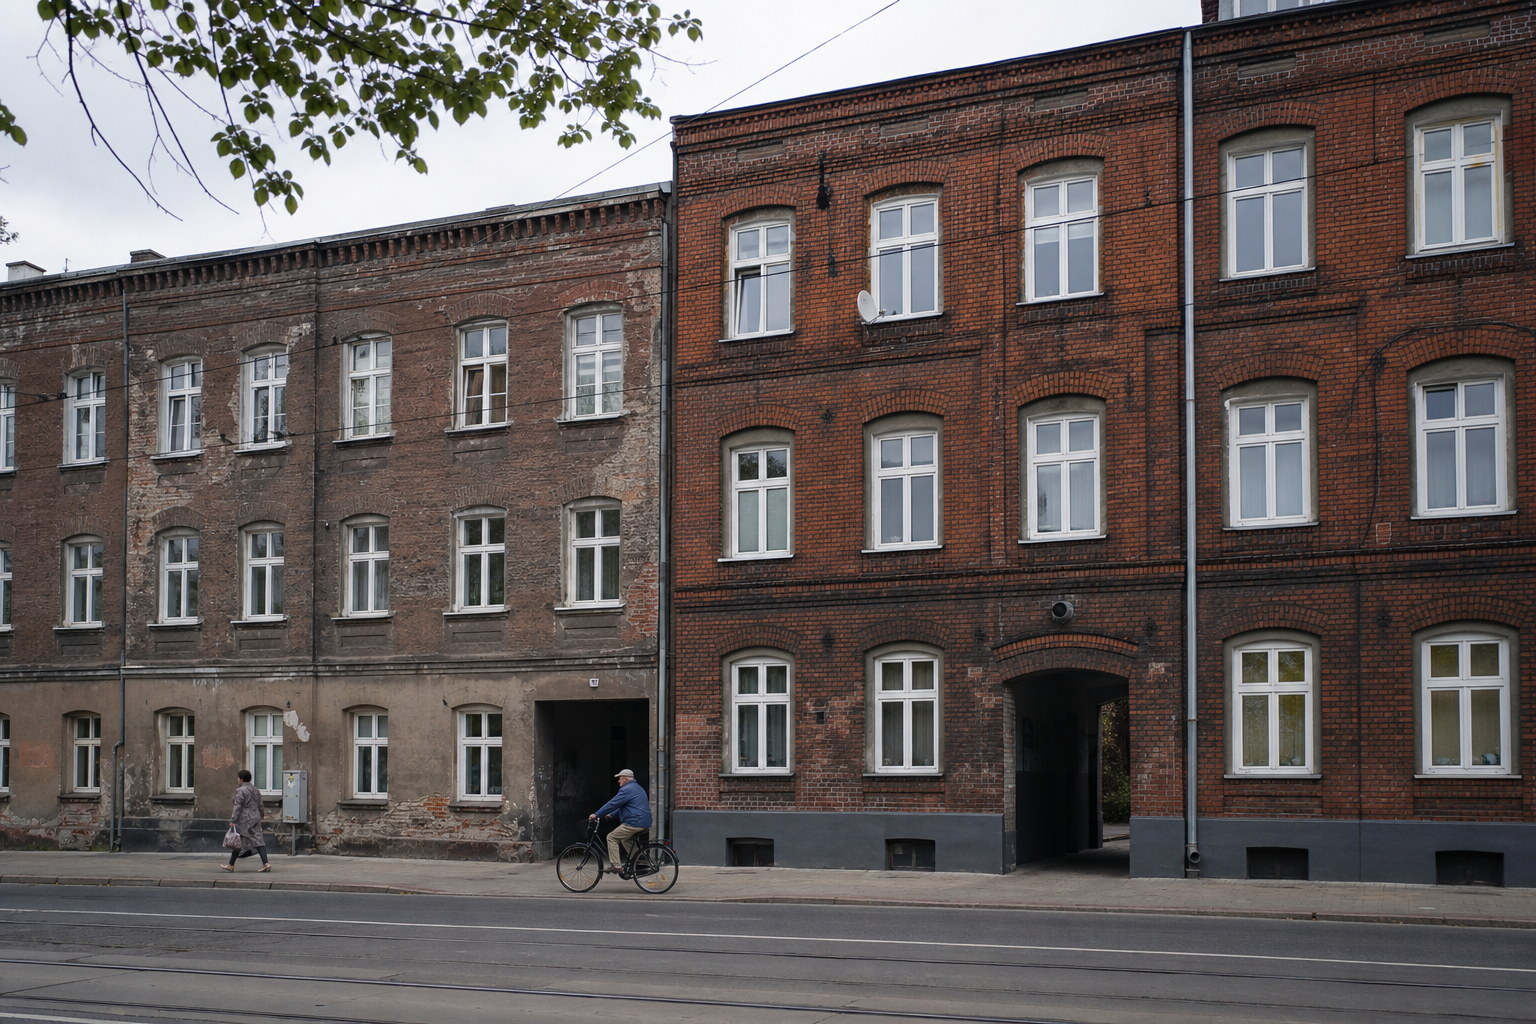
Praga
Historic stock, new projects and strong micro-location differences.
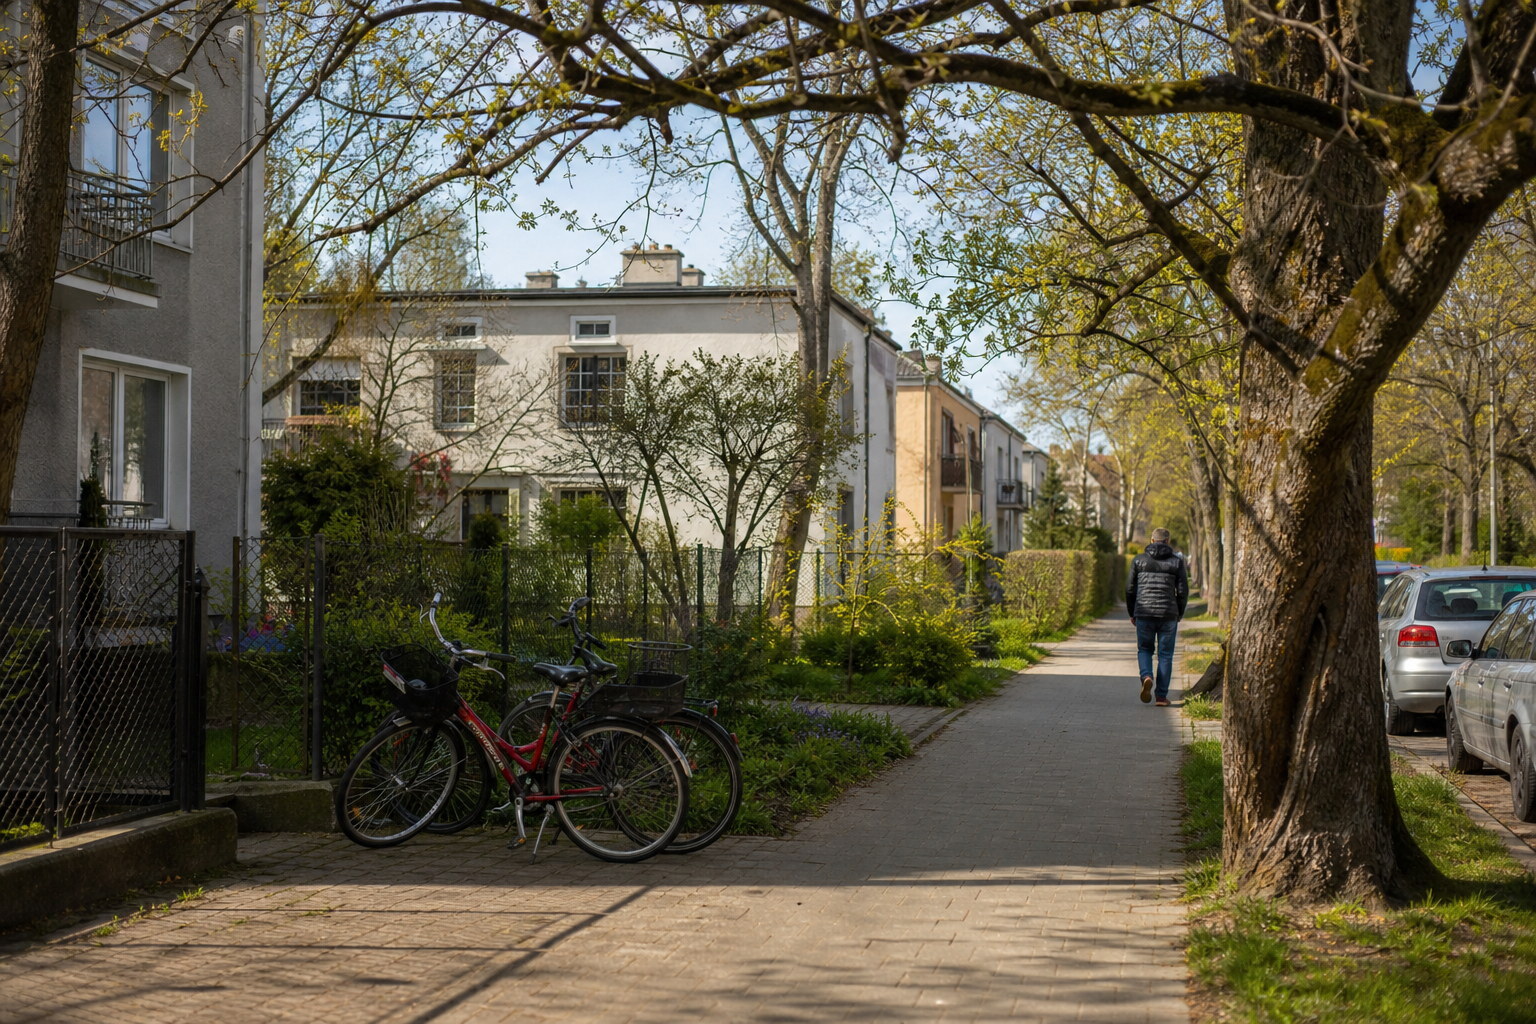
Żoliborz
Limited supply, greenery and strong owner-occupier appeal.
Price should follow the use case. A relocating family may value school access, parks, storage and a reliable commute more than a central postcode. A rental buyer may need a layout and transport relationship that future tenants can understand immediately. An owner planning a later resale should ask who else will want the apartment, not only whether the current buyer likes it.
Our Warsaw area guides cover 17 buyer routes. They are a starting map, not a substitute for checking the exact street, building, title and competing stock.
Similar citywide averages can conceal completely different purchase risks.
The stronger market depends on the apartment, timeline and capital needed after signing.
 New build: developer, completion stage, fit-out and handover risk.
 Resale: title, condition, building history and negotiation evidence.
More supply does not mean identical value
Compare construction stage, developer documentation, payment schedule, handover standard, exposure, future surroundings and the full finishing budget. Parking and storage may be mandatory additions.
Existing condition must be priced honestly
Review ownership, land register, building finances, service charges, technical systems, renovation history, furniture value and the seller’s real timing or constraints.
CBRE reported 16,345 new apartments on offer in Warsaw at the end of Q2 2026, up 7.1% quarter on quarter. Developers launched 4,753 units and sold 3,840 during the quarter. Completed but unsold stock represented 20.5% of the offer. This does not make every completed unit attractive, but it gives selective buyers more reason to compare readiness, incentives and time on market.
CBRE’s Q2 new-build asking average was PLN 19,405/m², while NBP’s primary-market offer average was PLN 18,488/m². The difference is a useful lesson: two credible sources can report different averages because scope, timing, exclusions and methodology differ. A buyer should understand the source before applying its number to a property.
Market supply source: CBRE Warsaw and Poland Living Figures Q2 2026. Continue with WIC’s new-build vs resale comparison.
What makes one apartment worth more than the average?
Price per square metre is only the output of many smaller decisions.
 The best purchase is rarely the listing closest to the average. It is the property whose price matches its evidence and risks.
The final 300 metres
Traffic, tram noise, views, crossings, commercial activity, station entrance and the route home can change demand within the same neighbourhood.
Costs and future works
Lift, façade, roof, installations, reserve fund, parking, common areas and community decisions affect both comfort and future owner expense.
Usable layout over nominal area
Light, exposure, room proportions, storage, structural limits and circulation determine how much of the purchased area works in practice.
Title and seller authority
Ownership form, land register entries, mortgages, easements, occupancy and transaction authority can alter risk, timing and financeability.
Visible finish and hidden systems
Electrical, plumbing, ventilation, moisture, windows, heating and geometry matter more than fresh paint or staged furniture.
Who will rent or buy next?
A clear future user supports liquidity. An unusual layout, weak access or excessive service charge can narrow the audience even in a popular district.
WIC can reject a property that photographs well but fails the complete-cost, legal, technical or resale test. Our role is not to defend the listing; it is to protect the buyer’s decision and keep better options visible.
Send the listing link with your intended use. We can discuss whether it belongs on a serious shortlist and which questions should be answered before commitment.
The purchase price is not the final price of ownership.
A cheaper apartment can become the more expensive project after signing.
 Renovation and fit-out must be part of the acquisition model.
 Service charges and recurring costs affect rent and resale.
For a resale transaction, the buyer may need to budget for PCC where applicable, notary and court fees, legal or technical specialists, currency conversion, agency support, renovation, furniture, insurance and initial carrying costs. For a new build, PCC may not apply in the same way, but finishing, kitchen, lighting, wardrobes, appliances, parking and storage can create a large post-purchase capital requirement.
- Purchase costs: tax treatment, notarial fees, court registration, translations and professional review.
- Execution costs: fit-out, renovation, technical corrections, furniture, appliances and contingency.
- Holding costs: service charges, utilities, insurance, financing and vacancy before occupation or rent.
- Time cost: delayed handover, contractor schedule, document defects or a property that cannot generate income immediately.
- Exit cost: a layout or condition that requires another buyer to repeat the same expensive work.
Compare opportunities on an all-in basis. A PLN 30,000 discount can disappear quickly if the apartment needs PLN 100,000 more work than the alternative. Conversely, paying more for a finished property is not automatically rational if the finish has little value to the target tenant or owner.
Use the complete Warsaw purchase-cost guide, then compare the intended rental scenario with the Warsaw rental-yield calculator. WIC can coordinate the search, legal path, renovation or finishing and rental preparation as one connected project.
A wider offer rewards selection, not passive waiting.
Current data support comparison and negotiation, but not a universal market-timing claim.
 More supply creates comparison opportunities, but project quality and contract terms still vary.
The 2026 picture is not a simple boom-or-crash story. NBP’s Q2 average transaction prices rose moderately year on year, while asking prices rose faster. CBRE recorded a larger new-build offer, a record share of completed unsold units and sales still above the five-year quarterly average despite a decline from a particularly strong Q1.
For buyers, that combination means three things. First, there is no reason to treat every asking price as inevitable. Second, an apartment still needs to be good enough to justify its price; weak properties do not become strong merely because the city average increased. Third, the buyer should prepare financing, documentation and decision criteria before the right property appears, because genuinely attractive units can still move quickly.
Prepare the decision system
Set the total capital limit, purchase purpose, minimum layout, acceptable locations, technical tolerance and walk-away conditions before viewings.
Waiting for one citywide forecast
Warsaw submarkets can move differently. A future average cannot repair a weak building, poor layout, bad legal position or excessive acquisition cost.
The goal is not to buy “the Warsaw market.”
The goal is to buy one property whose price, risks and future demand work for your situation. Market data narrow the search. Due diligence and execution decide the purchase.
From a price benchmark to a controlled Warsaw purchase.
International buyers need one connected route from the first brief to the keys and post-purchase setup.
 A focused shortlist replaces endless portal browsing.
 Commercial interest never replaces legal verification.
Define the complete buyer brief
Budget, use, financing, time horizon, preferred districts, commute, condition tolerance and exit strategy become one search instruction.
Search and compare both markets
We review relevant resale listings and developer stock instead of limiting the buyer to one portal, one agent’s inventory or one district assumption.
Screen before time is spent
Location, layout, price, building, ownership information and visible risks are checked before weaker options consume viewings or travel time.
Inspect and position the offer
We organise viewings, record relevant details and build the negotiation around competing stock, condition, timing and transaction-specific evidence.
Coordinate legal and technical review
Appropriate specialists verify title, contracts, seller or developer documents, technical condition and any foreign-buyer or power-of-attorney requirements.
Complete and prepare the property
We can coordinate the notarial path, handover, utilities, renovation or finishing, furnishing, rental setup and ongoing management where the service fits.
 Price, terms, included items and timing form one offer.
 The apartment and the building both affect long-term value.
WIC is engaged by the buyer. We do not need to defend a developer’s project or a seller’s asking price. If the evidence does not support the property, the correct commercial decision can be to leave it and continue the search.
Use current evidence and keep its limitations visible.
This page is a market guide, not a valuation report for an individual apartment.
 Reliable decisions keep price data, property documents and complete costs in the same file.
Narodowy Bank Polski — BaRN
The principal price figures come from the official NBP workbook downloaded and checked on 4 September 2026. It contains average offer and transaction prices for multifamily residential premises and explains the survey timetable and methodology. NBP data are a Warsaw-wide benchmark and do not provide a valuation for one address.
CBRE — Warsaw and Poland Living Figures Q2 2026
CBRE provides a current view of Warsaw’s build-for-sale market: units offered, sold, launched, completed and unsold, plus its own offer-price measure. Its scope and methodology differ from NBP, so the two averages should not be merged.
WIC calculations
Quarterly and annual changes, offer-to-transaction differences and illustrative budget-to-area figures on this page were calculated from the displayed NBP Warsaw values. Values are rounded for readability.
Review the page when NBP publishes Q3 2026 data or when a later authoritative Warsaw market release materially changes the snapshot. District guides should retain their own source dates rather than silently inheriting this citywide update.
Warsaw property prices in 2026.
Direct answers for buyers starting or refining an apartment search.
What is the average apartment price in Warsaw in 2026?
For Q2 2026, NBP reported average transaction prices of PLN 16,783/m² on the primary market and PLN 16,723/m² on the secondary market. These are citywide averages, not district or property valuations.
What were Warsaw asking prices in Q2 2026?
NBP reported average offer prices of PLN 18,488/m² for the primary market and PLN 19,059/m² for existing stock. Another credible source can show a different average because methodology and sample scope differ.
Why is the average asking price higher than the transaction price?
Sellers and developers set starting prices, while transaction data record completed deals. Timing, property mix, negotiation and methodology differ. The gap between citywide averages is not a guaranteed discount on an individual listing.
Are new apartments more expensive than resale apartments in Warsaw?
Not universally. Q2 2026 NBP transaction averages were close, but district, project, completion stage, fit-out requirement and parking can change the complete cost. Compare equivalent properties and all capital required after purchase.
How much apartment can PLN 1 million buy in Warsaw?
At the Q2 citywide transaction averages, PLN 1 million equates mathematically to about 60 m² before purchase costs. Prime locations or premium projects may provide less; outer districts or properties requiring work may provide more.
Which Warsaw district is cheapest?
There is no durable answer without a date, property type and micro-location. Lower-entry districts can include very different rail access, building quality, future supply and technical risks. Compare current properties rather than relying on a permanent ranking.
Are Warsaw apartment prices still rising?
NBP’s Q2 2026 averages increased quarter on quarter on both primary and secondary markets. Annual transaction growth was moderate, while asking-price growth was stronger. Individual submarkets and properties can still behave differently.
Is 2026 a good time to buy in Warsaw?
The answer depends on the buyer’s use, time horizon, financing and the property available. Current supply supports comparison, but no citywide timing claim can make a weak apartment good. Buy when the specific property and complete cost pass the required tests.
Can a foreign buyer negotiate a Warsaw apartment price?
Yes, negotiation is possible, but the position should come from competing stock, condition, timing, seller or developer constraints and transaction evidence. A fixed percentage taken from city averages is not a reliable strategy.
How can Warsaw Investor Care help?
WIC provides buyer-side property search, shortlist comparison, viewings, negotiation and coordination of legal, technical, notarial and post-purchase work for international clients buying in Warsaw.
Turn your Warsaw budget into a property decision.
One conversation can establish whether the brief is realistic and which search routes deserve attention.
 From the first budget discussion to due diligence, closing and the keys.
Tell us what you want the Warsaw property to do.
Send your budget, intended use, financing method, timing and any districts or listings already under consideration. We will discuss the practical search route and where buyer-side support can add value.